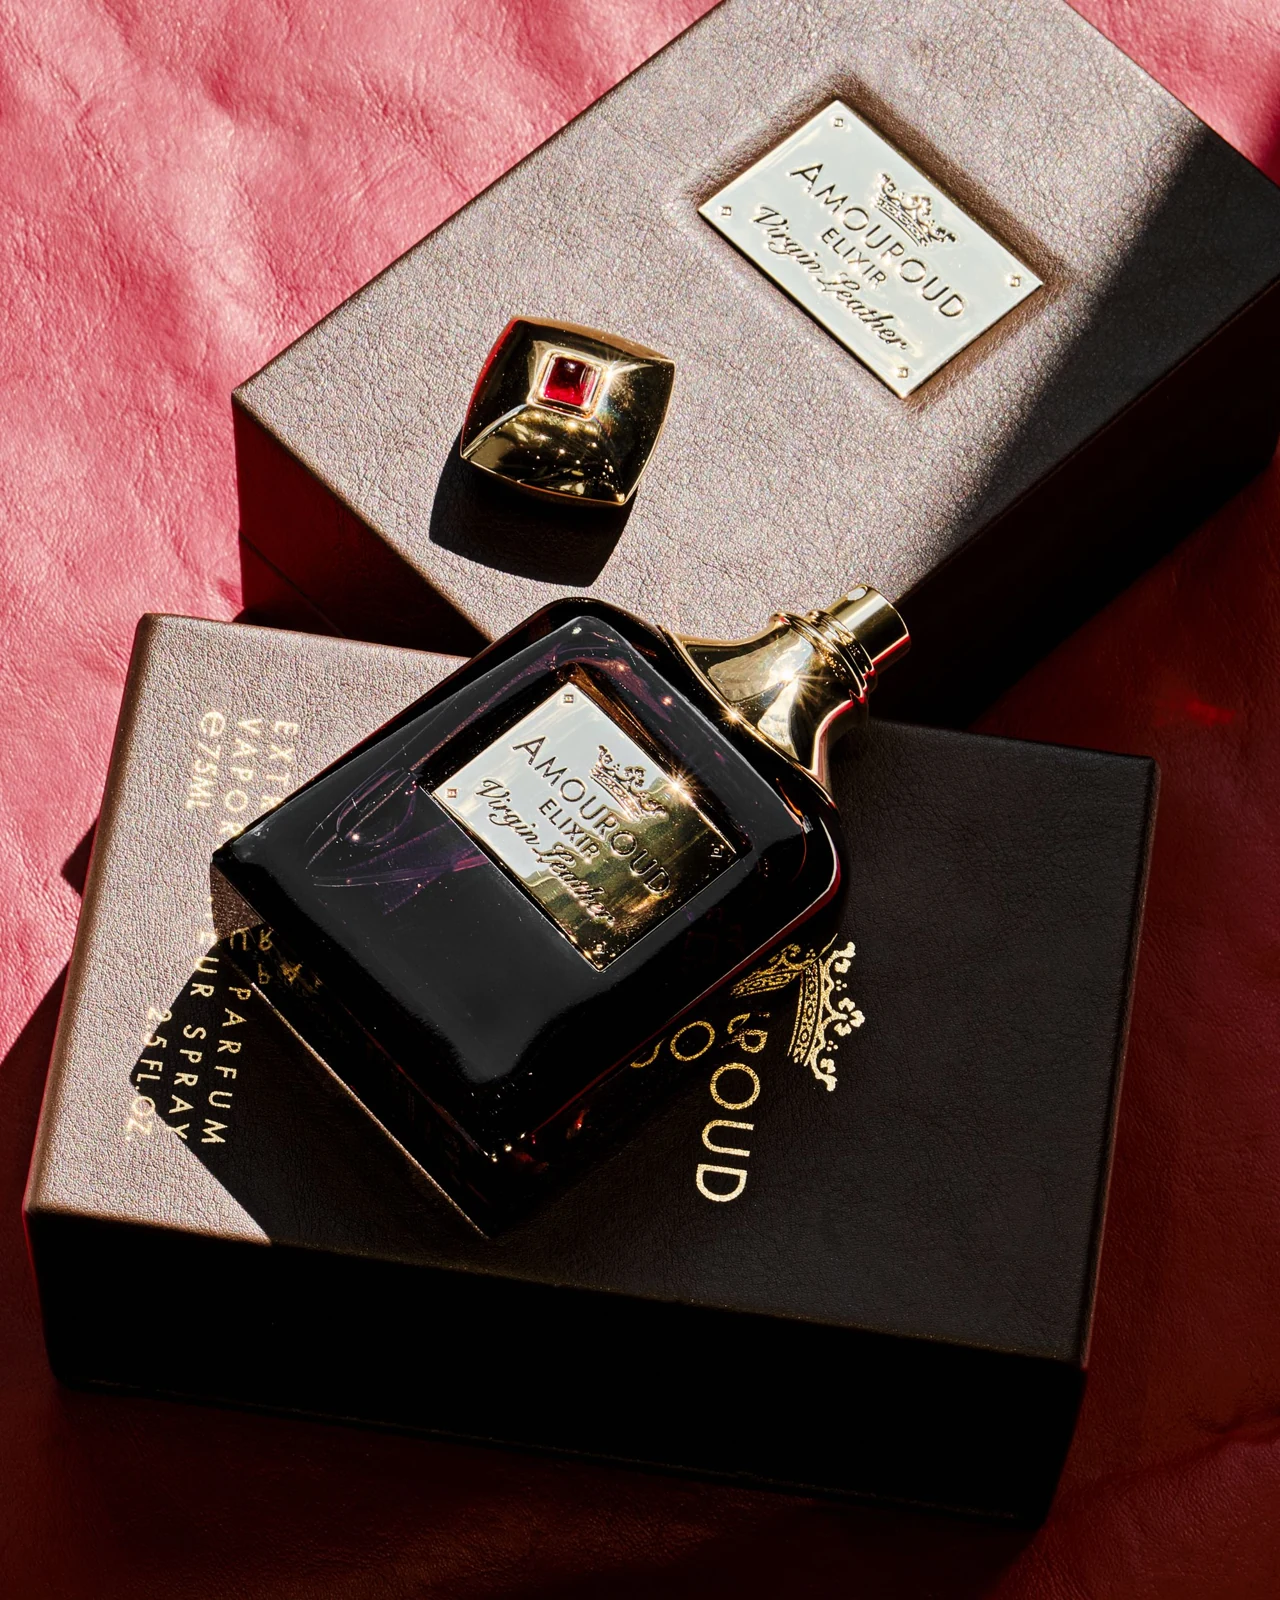
A bottle, cap and presentation boxes shown as an editorial reference for identifying the components of a packaging proposal. Photo by Malcolm Garret on Pexels. The photograph does not establish material specifications, manufacturing processes or prices. No brand endorsement, affiliation or Bravo Package project is implied.
PERFUME PACKAGING · COSTS AND BUDGETING
One perfume box quotation has a lower unit price. Another looks more expensive. Before choosing, check whether both include the same insert, finishes, assembly state and delivery destination. If their scope differs, the price gap does not yet tell you which order requires less spending.
A useful budget answers three questions: what are you buying, what will you pay for this order, and which costs or tasks remain unresolved? Connect those answers to quantities, specifications and handover conditions. This guide provides a budgeting framework rather than a price list detached from a real project.
Define the packaging you are buying
List the components: carton, insert, card, label, seal, bag and other accessories. Are bottles, pumps and caps purchased separately? A packaging quotation should not automatically be treated as the budget for a complete filled fragrance.
Identify the applicable SKU, capacity or bottle, structural and artwork revisions, material, finish coverage and quantity required per set. “Foil-stamped box” still leaves questions: where is the foil, which faces are printed, is an insert included, and who installs accessories? Link those details to drawings or approved information rather than inferring them from the price.
Confirm the delivery form too. Flat components, folding cartons awaiting assembly, formed boxes and boxes with inserts installed leave different work for the recipient. Identify who receives, assembles, packs products and prepares shipping cases. Some of that work may remain in the brand's own budget.
Separate development from the production order
Possible development items include visual design, structural work, file preparation, samples, sample delivery, revisions and manufacturing preparation. Different people may provide them, and some may already be complete. Ask what is actually needed and covered, rather than automatically adding a charge for every possible category.
Clarify any “plate” or “tooling” fee. What does it cover: a cutting die, print preparation, foil tooling or something else? How is it charged, and is it already included in the unit price? What deliverable or use arrangement accompanies payment? A broad label does not establish that every preparation cost is charged only once.
For expected reorders, ask about storage, applicability, modification and reuse conditions. An unchanged visual design does not prove that no further preparation is needed. Changes to size, material, process or supplier may require renewed confirmation. Record the order, conditions and amount attached to any promised sample-fee credit before deducting it from a budget.
Check the boundaries of free services as well: concepts, files, revision rounds, delivery charges, subsequent-order requirements and use arrangements. The issue is whether the work and conditions are clear, rather than whether a particular charging model is inherently better.
Read unit prices alongside specifications and quantities
Size, structure, material, printed faces, finishing areas, accessories and assembly requirements are quotation inputs. A lower price may represent a different configuration or making proposal. Ask the supplier to explain the difference, then assess suitability. Price alone does not establish quality.
Break quantities down by design, size, language, colour or other applicable variants. A total order spread across several versions may not qualify for the same pricing as one larger run of a single version. Request quantities, prices, included preparation and relevant conditions for each variant.
Obtain actual quotations for the quantity options you want to compare. Do not extrapolate prices proportionally or infer a supplier's true costs from two order totals and use the result to declare a quotation false. Different making and pricing arrangements may apply. The buyer needs an identifiable offer and payment scope.
Label unresolved structures and finishes as budget assumptions. If files and samples are still changing, identify whether the figure is an estimate or a quotation usable for the current order scope. That provides a baseline for later changes.
Include work remaining after receipt
Shipping cartons, protective materials, packing and transport may sit outside the box price. Mark each item included, separately charged, not applicable or awaiting confirmation. Record the payer and charging basis. Do not add an expense again if the supplier's total already covers it.
Transport quotations need the actual shipment form, packed dimensions and weight, case count, destination and handover conditions. Recheck after changes to quantity, split shipments or delivery locations. Ask the relevant provider to explain charges, taxes, insurance or cross-border arrangements for the transaction; do not apply a universal divisor or percentage found online.
Give a budget location to internal or third-party assembly, sorting, storage, samples, checking and replacement work where the project requires it. Distinguish confirmed tasks from possible expenses. A potential issue is not an inevitable loss, but work omitted from a box supplier's quote does not disappear.
Revisit requirements when reducing costs changes the pack. Removing an insert, substituting material or altering shipment packaging does not establish equivalent performance simply because the price falls. Identify the changes and necessary checks before accepting the proposal.
Review both order spending and project spending
The first view is this order's purchasing expenditure. Under consistent currency, quantity, tax and delivery assumptions, total the accepted quotation lines and confirmed separate charges. Count each once. Keep unanswered items open rather than filling them with zero. Reconfirm affected figures when quotation validity or conditions change.
The second view is the project budget. Add required design, receiving, storage and other work that is not already covered. Show initial expenditure, costs recurring with orders and possible future costs separately. A single unit figure should not hide all those assumptions.
When comparing spending per set, name the denominator: ordered quantity, received quantity, confirmed usable complete packaging sets, or planned future sales? These are different figures. A planning estimate can use planned quantities, but actual records should replace assumptions after receipt.
Ask the responsible operators to identify additional items needed for samples, checks, setup or replacements. Do not invent a standard wastage allowance. If an issue occurs, record its actual effect and avoid counting the same item repeatedly in an allowance, a replacement order and the usable-quantity calculation.
Use a budget comparison checklist
| Budget area | Scope information | Confirm the charging basis | Avoid assuming |
|---|---|---|---|
| Packaging components | SKU, revision, quantity per set, materials and making scope | Quantity and included or separate status for each line | Missing inserts or accessories make box-only prices incomplete comparisons. |
| Development and samples | Design, structure, files, samples, delivery and revision scope | Deliverables, charging basis and existing work | Free does not mean unlimited; existing work may need review. |
| Tooling and preparation | Actual work, associated revision, storage and reuse conditions | Current charges, included status and later conditions | Do not assume permanent reuse or exclusively one-time fees. |
| Assembly and delivery | Flat or formed state, accessories, shipping cases and destination | Remaining recipient work and transport basis | Included freight does not cover every later expense. |
| Project-side work | Checks, assembly, storage, samples and replacement purposes | Operator, confirmed tasks and unresolved estimates | Possible expenditure is separate from confirmed spending. |
| Changes and review | Revised materials, processes, quantities, files and delivery terms | New quotation, differences and approval record | Do not budget a changed order using old prices or unconfirmed credits. |
Give suppliers the same scope description and let them explain what they can offer. Where configurations cannot match exactly, put the differences beside the prices. Different proposals can still be considered, provided you understand what the price buys and what remains to be done.
Manage changes instead of relying on a reference price
Keep the baseline proposal. For each revision, record the change, reason, affected components, quoted difference and attributes needing another check. Link the new quote to its revision and quantity, and confirm whether the previous offer remains valid. Artwork, messages and pricing should not describe three different versions.
On a reorder, review which development outputs remain applicable, which preparation needs repeating, and whether quantities or delivery arrangements have changed. Previous payments need traceable records, but do not automatically establish present applicability or free reuse. New charges should identify the actual work they cover.
A dependable budget does not require precise-looking guesses. It shows amounts with defined scope, items still awaiting a quote, conditions that could change the total and the person responsible for the next confirmation. That makes perfume packaging cost a manageable project decision rather than a collection of apparently comparable box prices.
Clarifying quantities across several variants? Our perfume packaging MOQ guide explains which design, size or component a minimum governs, with a table for confirming each variant and any accepted combination.
Comparing different order quantities? Our perfume box unit cost and quantity guide helps align specifications, preparation charges, delivery terms and total expenditure before choosing a quantity.
Checking preparation charges? Our perfume packaging tooling and setup cost guide covers the scope of cutting-die, foil-die and development fees, with a checklist for deliverables, revisions, storage and later orders.
Choosing a small-run packaging proposal? Our stock boxes versus custom perfume packaging guide compares actual box restrictions, labels, application, samples and delivered scope before choosing a small-run solution.
Considering common packaging across fragrances? Our shared fragrance box structures guide explains how to compare component, artwork, insert and quotation scope before attributing savings to shared structures.
Allocating a limited packaging allowance? Our small perfume packaging budget guide explains how to compare paper, inserts and finishes against actual product requirements and complete quotations.
Reviewing what an offer leaves out? Our perfume packaging quote exclusions guide explains how to check components, samples, tools, assembly and delivery without treating every exclusion as an undisclosed charge.